The power to arrest under GST has always been one of the more contentious parts of the law. Can the GST Department arrest a person even before tax liability has been formally determined? And if it can, how much evidence must the Commissioner have before exercising such a serious power?
A recent discussion around the Supreme Court’s ruling in Radhika Agarwal v. Union of India has brought these questions back into focus. The Supreme Court has clarified an important position: a completed GST assessment or adjudication is not a mandatory prerequisite for arrest under Section 69 of the CGST Act. However, that does not mean arrest can be based merely on suspicion or a preliminary allegation. The Commissioner must have credible material supporting a genuine “reason to believe” that a specified GST offence has been committed.
For businesses, promoters and finance professionals, this distinction is significant. The Court has upheld the Department’s power to act before adjudication, but at the same time has placed meaningful safeguards around how that power must be exercised.
Why Is Section 69 of the CGST Act Important?
Section 69 of the CGST Act empowers the Commissioner to authorise the arrest of a person where there are reasons to believe that the person has committed specified offences under Section 132.
These offences broadly include serious cases involving tax evasion, issuance of invoices without actual supply, fraudulent availment of Input Tax Credit and collection of tax without depositing it with the Government.
For specified offences involving amounts above the statutory threshold, the consequences can extend beyond tax recovery and penalty to criminal prosecution and imprisonment. In serious cases covered by Section 132(5), the offence can also become cognizable and non-bailable.
This makes the power under Section 69 fundamentally different from an ordinary GST demand proceeding.
A normal GST dispute usually follows a recognisable sequence: investigation or scrutiny, issuance of a show cause notice, adjudication, determination of liability and thereafter recovery or appeal.
Arrest can potentially come much earlier.
And that is precisely where the legal controversy arose.
Can GST Arrest Take Place Before Adjudication?
Taxpayers had argued that arrest should not normally take place until the alleged tax liability has first been determined through adjudication.
The argument has considerable practical force. If the amount of alleged tax evasion has not yet been finally determined, how can the Department conclude that an offence crossing the prescribed monetary threshold has actually occurred?
The Supreme Court has now clarified that formal crystallisation of tax liability is not essential before arrest.
In Radhika Agarwal, decided on 27 February 2025, the Court held that where sufficient material already exists to establish, with the required degree of certainty, that an offence under Section 132 has been committed, the Commissioner can exercise the power of arrest without waiting for completion of the assessment or adjudication process.
However, this is only half of the principle laid down by the Court.
“Reasons to Believe” Cannot Mean Mere Suspicion
The more important protection for taxpayers lies in the expression “reasons to believe.”
The Supreme Court made it clear that this requirement cannot become a routine formality. The Commissioner cannot simply reproduce the language of Sections 69 and 132 and authorise an arrest.
There must be material on record supporting the belief that the relevant offence has actually been committed.
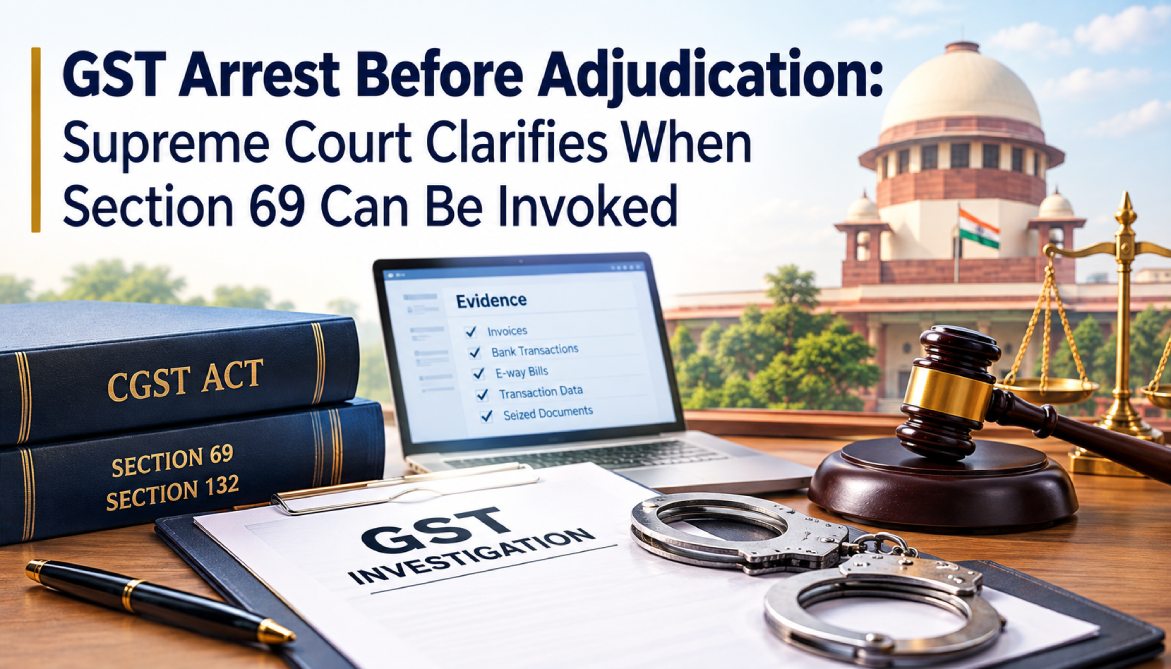
Such material could include invoices, seized documents or goods, bank transactions, statements, e-way bill records, transaction data or other measurable evidence discovered during investigation. The available material should also enable the Department to arrive at a reasonable working estimate of the alleged evasion.
In other words, the GST Department does not necessarily need a final adjudication order.
But it does need something considerably stronger than an allegation.
That distinction is critical.
Monetary Thresholds Still Matter
Section 69 operates together with Section 132 of the CGST Act. Therefore, the nature of the alleged offence and the amount involved remain central to the legality of an arrest.
The Supreme Court specifically noted that for the serious categories of GST offences treated as cognizable and non-bailable, the statutory monetary conditions under Section 132 must be met.
Accordingly, there should ordinarily be some evidence-based quantification available with the authorities to demonstrate that the alleged offence falls within the relevant monetary bracket.
This does not require the precision of a final assessment order. But it does require a reasoned connection between the evidence gathered and the amount of alleged tax evasion or wrongful ITC.
Written Grounds of Arrest Are Another Important Safeguard
The judgment also reinforces procedural safeguards surrounding GST arrests.
The grounds of arrest must be communicated to the person being arrested. CBIC’s January 2025 instruction also requires these grounds to be furnished in writing as an annexure to the arrest memo. The Supreme Court linked such safeguards to the protection of personal liberty and the ability of an arrested person to effectively challenge the arrest or seek bail.
The Court also reiterated a broader principle that is particularly relevant in GST investigations: the existence of a power to arrest does not automatically justify its exercise.
An arrest should not become mechanical merely because the statutory ingredients appear to be satisfied.
What Does the Supreme Court Ruling Mean for Businesses?
The decision creates a carefully balanced position.
For the GST Department, it confirms that investigation and arrest powers are not dependent upon completion of adjudication. This can be especially relevant in cases involving suspected fake invoices, fraudulent ITC networks or deliberate tax evasion where authorities believe immediate action is required.
For taxpayers, however, the ruling provides an equally important protection: Section 69 arrest cannot rest on vague suspicion, standard language or unsupported assumptions.
There should be identifiable material, recorded reasons and an evidence-based basis for concluding that the conditions under Section 132 are satisfied.
Courts can still examine whether these statutory safeguards were followed, although judicial review does not mean that the High Court will conduct a full reassessment of the underlying GST dispute.
The Key Takeaway
The question after the Supreme Court ruling is therefore no longer simply:
“Has tax liability been adjudicated before arrest?”
The more relevant question is:
“What credible material did the Commissioner have before forming the reason to believe that an arrest was justified?”
That shift is significant.
The Supreme Court has preserved the GST Department’s power to arrest before adjudication, but it has simultaneously emphasised that personal liberty cannot be curtailed on the basis of suspicion alone.
For businesses facing GST investigation proceedings, the quality of the evidence, the quantification of the alleged offence and the reasons recorded by the authorities may therefore become just as important as the eventual tax demand itself.