As AI tools such as ChatGPT have become part of everyday individual users, business operations, Indian companies and even for professionals who are are increasingly utilizing the service provided by the foreign service provider, integrating enterprise access and APIs, drafting an e-mail, analysing a spreadsheet, reviewing code or brainstorm a presentation.
And for all this stuffs we pay subscription.
As a result invoice comes from an overseas technology company.
And that is where the tax story begins.
What often looks like a simple monthly software expense can actually raise questions under GST, Reverse Charge Mechanism, OIDAR rules and Income-tax withholding provisions.
So, if your business pays for ChatGPT or another overseas AI platform, then there arise many questions
- who pays GST?
- Can the business claim Input Tax Credit?
- Is TDS required?
- And does it make a difference whether you are using the tool personally or commercially?
So let us understand that how does GST see a ChatGPT Subscription, where understanding of all these questions can be captured:
For tax purposes, ChatGPT is not looked merely as an “AI tool”.
The most relevant element for taxation is how the services are delivered.
Standard AI platforms are accessed online, operate through digital infrastructure, generate outputs automatically and involve little or no human intervention in delivering each individual response.
These characteristics bring such services within the broad framework of Online Information and Database Access or Retrieval services — commonly known as OIDAR services under the IGST Act.
This category is important because India has specific GST rules for digital services supplied from outside India to customers located in India.
And the tax treatment changes significantly depending on who is using the AI service.
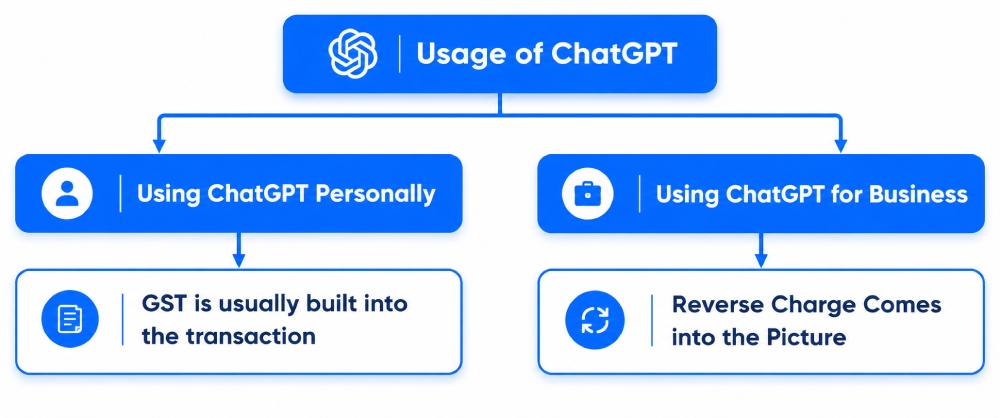
Suppose an individual in India purchases an AI subscription for personal use and is not registered under GST.
In such a case, the overseas digital service provider generally has the responsibility to collect and discharge IGST under the mechanism applicable to OIDAR services supplied to an unregistered customer in India.
So, for the user this is relatively straightforward. You purchase the subscription, tax is charged as applicable, and there is no Input Tax Credit because the service is being consumed personally.
Now, suppose an Indian company, LLP, CA firm, software developer or another GST-registered business purchases an AI subscription from an overseas vendor.
In such a case, the foreign vendor may issue an invoice without charging Indian GST. But this does not necessarily mean that there is no GST Liability.
The Indian business may instead be required to pay IGST itself under the Reverse Charge Mechanism (RCM) as an import of service. And the applicable GST rate would be 18%.
Let’s Consider an Example:
If an Indian company spends ₹10 lakh annually on AI subscriptions or API access, an 18% RCM liability would amount to ₹1.8 lakh.
Therefore, the company would pay that GST through the prescribed mechanism and, if the service is used for business and all ITC conditions are satisfied, then it may generally
claim the corresponding Input Tax Credit.
Now, this is where the Economics becomes more interesting
For an eligible business, the GST paid under RCM may be largely tax-neutral because the same amount can potentially come back as ITC.
Whereas, for a personal user, there is no such credit.
Isn’t this amazing: Same AI tool, but different tax outcome, based on its user and usage.
What About ChatGPT API and Enterprise Plans?
Many Indian technology companies are now integrating foreign AI APIs into their own software, customer-service platforms, automation tools and internal applications. Purchasing of enterprise workspace for dozens or hundreds of employees is also increasing over the period.
From, a GST perspective the underlying logic for a ChatGPT subscription or integration of API and other enterprise plans remains unchanged: Where a GST-registered Indian entity procures electronically supplied AI services from an overseas provider, the transaction may constitute an import of service and attract GST under RCM, subject to the precise facts and contractual arrangement. This awakens Businesses to look beyond the corporate card transaction.
On the other hand, the accounting and tax teams should tighten up their seats to know about:
- who the contracting entity is;
- where the vendor is located;
- whether GST has already been charged;
- whether RCM applies;
- whether eligible ITC has actually been claimed.
Otherwise, an innocent-looking SaaS or AI subscription can turn up into a turbulence resulting into a recurring compliance gap.
Then comes a Bigger Question: Is TDS Deduction required?
A payment from an Indian business to a foreign AI service provider can also raise questions under the Income-tax Act and the relevant Double Taxation Avoidance Agreement (DTAA).
The core issue is whether payment can be characterised as Royalty or Fees for Technical Services / Fees for Included Services.
The distinction matters because such characterisation can affect withholding obligations under Section 195 of Income Tax Act, 1961 and SI No. 17 of section 393(2) of Income Tax Act,2025
A view can be taken that an ordinary access to an AI platform — without transfer of source code, copyright or proprietary technology — may generally be distinguished from a royalty payment.
In practical terms, paying to use ChatGPT is not the same thing as acquiring ownership or rights over the technology. Instead, you are buying access and not the model.
Hence, understanding this difference is important in terms of TDS under Income Tax Act.
Now, comes a fun fact that whether a response from AI tends to be a Technical Service?
This is where the discussion becomes more interesting.
Traditional technical-service taxation often involves some element of specialised human intervention or expertise.
But with AI, the response is produced automatically by software. There may be no engineer, consultant or subject-matter expert, personally delivering the response at the other end.
Therefore, fully automated AI services may, not automatically fit the traditional characterisation of Fees for Technical services. Further, where the payment for AI services is not taxable as Royalty or FTS/FIS and the foreign provider does not have a Permanent Establishment in India, then Section 195 of Income Tax Act,1961 withholding may not necessarily arise.
But this is one area where businesses should resist applying a blanket rule and have a check over the contract terms, service package, jurisdiction of the provider and DTAA rules.
So, there is nothing wrong in saying that GST and Income-tax rules look not only at what was purchased, but also at who purchased it, from whom, how it is delivered and what rights or services the contract provides.
What should Indian Businesses Do?
For most businesses, the compliance is not complicated if the process is set up correctly.
The bigger risk is simply forgetting that these subscriptions are cross-border procurements.
Businesses using ChatGPT, AI APIs or similar overseas digital platforms should:
- maintain proper vendor invoices
- ensure the correct legal entity
- Whether GSTIN are reflected where relevant
- Evaluate RCM Liability
- Claim Eligible ITC, and
- Review whether any foreign-remittance or withholding-tax compliance is required
As AI spending grows, what was once a ₹2,000 monthly software subscription can quickly become a much larger enterprise technology cost. At that point treating it as “just another credit-card expense” is no longer enough.
The Bigger Takeaway
AI may actually feel borderless and truly it is, but Tax Law is not.
A prompt may travel to a foreign server and return an answer in seconds, but the payment behind that interaction can still trigger very traditional questions around GST, imports of services, reverse charge, ITC, royalty and withholding tax.
So, the next time someone in your organisation says:
“We just bought a ChatGPT subscription”
The Finance team rather than merely treating it as a business expense, should wake up and ask one more question:
“Personal usage, Business Subscription or API?”
Because from tax perspective, the detail could change everything
What You Need to keep in Mind
Overseas AI subscriptions such as ChatGPT may fall within the OIDAR / digitally supplied services framework under GST.
For unregistered personal users, GST may generally be collected by the overseas provider under the applicable mechanism.
GST-registered Indian businesses may need to pay IGST under RCM on overseas AI services and can potentially claim eligible ITC.
Standard AI access does not automatically mean a royalty payment for Income-tax purposes; the rights granted under the contract matter.
TDS under Section 195 should be evaluated based on the nature of the payment, the relevant DTAA and the foreign service provider’s tax position.
As enterprise adoption of AI grows, businesses should bring AI subscriptions and API payments into their regular GST and foreign-remittance compliance processes.