Post Single Template #2
- Home
- Post Single Template #2
Recent Industry News
1. Introduction
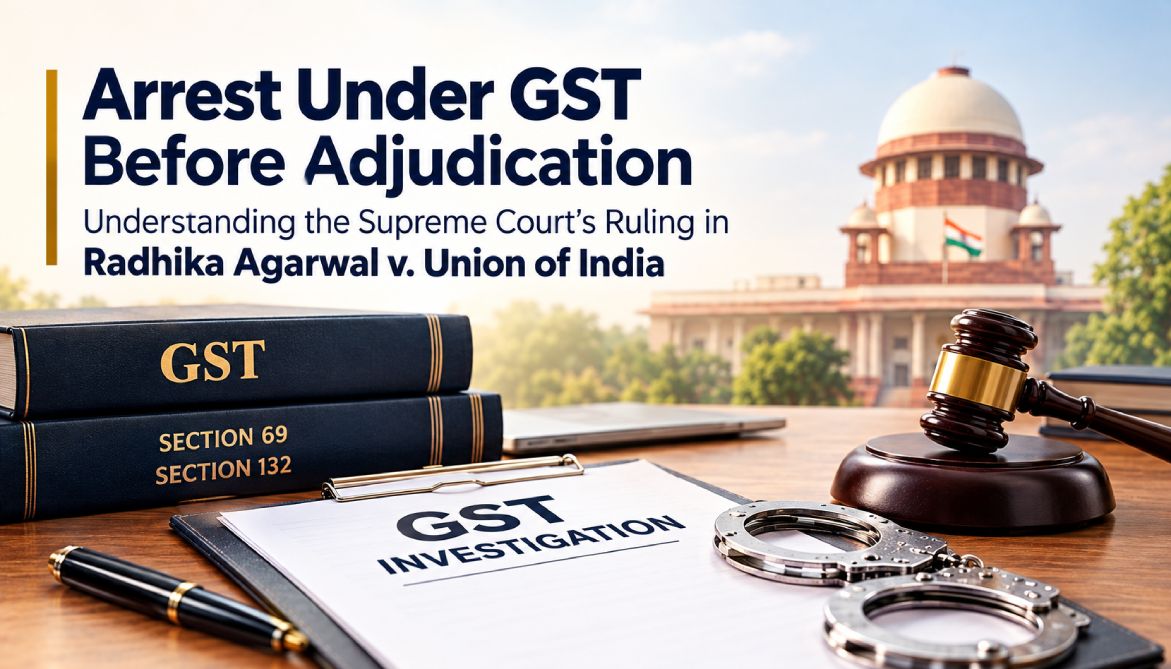
The power to arrest under GST has always been one of the more contentious parts of the law. Can the GST Department arrest a person even before tax liability has been formally determined? And if it can, how much evidence must the Commissioner have, before exercising such a serious power?
The Honourable Supreme Court’s ruling in the case of Radhika Agarwal v. Union of India [(2025) 27 Centax 425 (S.C.)], delivered on 27.02.2025 remains the leading authority on these questions. The Honourable Supreme Court clarified an important position: a completed GST assessment or adjudication is not a mandatory prerequisite for arrest under Section 69 of the CGST Act. However, that does not mean arrest can be based merely on suspicion or a preliminary allegation. The Commissioner must have credible material supporting a genuine “reason to believe” that a specified GST offence has been committed.
For businesses, promoters and finance professionals, this distinction is significant. The Honourable Supreme Court has upheld the Department’s power to act before adjudication but at the same time has placed meaningful safeguards around how that power must be exercised.
2. Why Is Section 69 of the CGST Act Important?
Section 69 of the CGST Act empowers the Commissioner to authorise the arrest of a person where there are reasons to believe that the person has committed specified offences under Section 132.
2.1 The Four Arrestable Offences
These offences broadly include four categories of offence, like:
- Supply of Goods or services without an invoice with an intent to evade tax
- Issuing invoices without actual supply
- Availing Input Tax Credit on such invoices or fraudulently without any invoice
- Collecting tax but failing to pay it to the Government beyond three months from the due date
2.2 How Arrest Differs from an Ordinary GST Dispute
For specified offences involving amounts above the statutory threshold, the consequences can extend beyond tax recovery and penalty to criminal prosecution and imprisonment. This makes the power under Section 69 fundamentally different from an ordinary GST demand proceeding.
A normal GST dispute usually follows a recognisable sequence: investigation or scrutiny, issuance of a show cause notice, adjudication, determination of liability and thereafter recovery or appeal.
Arrest can come much earlier and that is precisely where the legal controversy arose.
3. Can GST Arrest Take Place Before Adjudication?
3.1 The Taxpayers’ Argument
Taxpayers had argued that arrest should not normally take place until the alleged tax liability has first been determined through adjudication.
The argument has considerable practical force. If the amount of alleged tax evasion has not yet been finally determined, how can the Department conclude that an offence crossing the prescribed monetary threshold has actually occurred?
3.2 What the Supreme Court Held
The Honourable Supreme Court has clarified that formal crystallisation of tax liability is not essential before arrest under GST law. The Honourable Supreme Court held that where sufficient material already exists to establish, with the required degree of certainty, that an offence under Section 132 has been committed, the Commissioner can exercise the power of arrest without waiting for completion of the assessment or adjudication process. The Court was careful to frame this as an exception rather than the norm. It observed that assessment proceedings would normally quantify the tax evaded and rejected the taxpayers’ argument only “as a general or broad proposition”, recognising that “there could be cases” where the Department is sufficiently certain of the offence and the amount without a formal assessment.
However, this is only half of the principle laid down by the Court.
4. “Reasons to Believe” Cannot Mean Mere Suspicion
4.1 What the Court Required
The more important protection for taxpayers lies in the expression “reasons to believe.”
The Honourable Supreme Court made it very clear that this requirement cannot become a routine formality. The Commissioner cannot simply reproduce the language of Sections 69 and 132 and authorise an arrest.
There must be sufficient degree of material on record supporting the belief that the relevant offence has actually been committed.
The Court put it plainly: the exercise must not rest on mere ipse dixit and an arrest cannot be made merely to investigate whether the statutory conditions are being met. It also held that the principle of benefit of doubt applies and must not be ignored either by the Commissioner or by the Magistrate before whom the arrested person is produced.
4.2 What Kind of Material?
In practice, such material could include invoices, seized documents or goods, bank transactions, statements, e-way bill records, transaction data or other measurable evidence discovered during investigation. The available material should also enable the Department to compute the alleged evasion with a sufficient degree of certainty, since the Court required the computation to be supported by relevant and sufficient material.
In other words, the GST Department does not necessarily need a final adjudication order. But it does need something considerably stronger than an allegation and not mere suspicion.
5. Monetary Thresholds Still Matter
Section 69 operates together with Section 132 of the CGST Act. Therefore, the nature of the alleged offence and the amount involved remain central to the legality of an arrest.
The Honourable Supreme Court recorded the Revenue’s own submission that arrests are made only where the offence is cognizable and non-bailable. It then held that no arrest should be made until the Commissioner can show on the basis of material and evidence that the offence falls within clauses (a) to (d) of Section 132(1) and that the amount involved exceeds Rs. 5 crores.
Accordingly, the Commissioner’s recorded reasons should contain an evidence-based computation demonstrating that the alleged offence falls within the relevant monetary bracket. This does not require the precision of a final assessment order. But it does require a reasoned connection between the evidence gathered and the amount of alleged tax evasion or wrongful ITC.
6. Written Grounds of Arrest Are Another Important Safeguard
6.1 Written Grounds of Arrest
The judgment also reinforces procedural safeguards surrounding GST arrests.
The Honourable Supreme Court held that the grounds of arrest must be given to the arrested person in writing before he or she is produced before the Magistrate. CBIC’s Instruction No. 01/2025-GST dated 13.01.2025 is consistent with this and requires the written grounds to be annexed to the arrest memo with an acknowledgement taken from the arrested person. The Honourable Supreme Court linked such safeguards to the protection of personal liberty and the ability of an arrested person to effectively challenge the arrest or seek bail.
6.2 Safeguards under the Code of Criminal Procedure
The Court further held that the arrest safeguards in the Code of Criminal Procedure apply to arrests by GST officers. These include compliance with the D.K. Basu (supra) guidelines, informing a relative or friend nominated by the arrested person, the right to meet an advocate during interrogation (who may watch from within sight but not within hearing) and the duty to take reasonable care of the arrested person’s health and safety. Since the CrPC has been replaced by the Bharatiya Nagarik Suraksha Sanhita, 2023 with effect from 1 July 2024, these safeguards should now be read with the corresponding BNSS provisions.
6.3 Power to Arrest vs. Justification for Arrest
The Court also endorsed CBIC’s arrest guidelines (Instruction No. 02/2022-23 dated 17.08.2022), which draw on an earlier Supreme Court ruling to state a principle particularly
relevant in GST investigations: the existence of a power to arrest does not automatically justify its exercise. An arrest should not become mechanical merely because the statutory ingredients appear to be satisfied.
7. Protection Against Coerced Payments and Access to Anticipatory Bail
7.1 Coerced Payments
One of the most practical parts of the judgment deals with taxpayers being pressured to pay tax to avoid arrest. After examining the Department’s own data, the Court found some force in this complaint. It held that Section 74(5) gives the taxpayer an option to pay voluntarily and does not permit officers to compel or extract tax by threatening arrest, which would be unacceptable and violative of the rule of law. Where tax is deposited under threat, force or coercion, the taxpayer may approach the courts for a refund, and the Department is expected to take action against the officers concerned.
7.2 Anticipatory Bail
The Court also confirmed that anticipatory bail can be sought whenever there is a reasonable apprehension of arrest based on clear facts, even before any FIR or complaint is filed. This principle was confirmed recently by a Constitution Bench of Five Judges of this Court in Sushila Aggarwal v. State (NCT of Delhi) (2020) 5 SCC 1. Further earlier GST decisions taking a contrary view, including State of Gujarat v. Choodamani Parmeshwaran Iyer and Bharat Bhushan v. Director General of GST Intelligence are not to be treated as binding on this point.
7.3 Limits of the Ruling
At the same time, the ruling has limits that taxpayers should keep in mind. A person summoned under Section 70 is not treated as an accused entitled to protection under Article 20(3) at the stage of interrogation and the Court upheld the constitutional validity of Sections 69 and 70 as ancillary to the power to levy and collect GST under Article 246A.
8. What Counts as “Credible Material”? Guidance from Earlier Supreme Court Rulings
Radhika Agarwal requires the Commissioner’s reasons to believe to rest on material and evidence, not suspicion. The judgment does not list what qualifies. However, earlier rulings of the Honourable Supreme Court on evidence in tax and criminal matters give useful guidance. This matters because GST arrest cases typically rest on three kinds of material: statements recorded under Section 70, statements of other persons in an alleged fake-invoice chain, and records seized during search.
The starting point is an old principle. Suspicion, however strong, cannot take the place of evidence (Umacharan Shaw & Bros. v. CIT, [1959] 37 ITR 271 (SC); Union of India v. H.C. Goel, AIR 1964 SC 364). Radhika Agarwal gives this principle statutory force at the arrest stage. By adopting Arvind Kejriwal v. Directorate of Enforcement, it also held that the belief must be formed on material capable of being admissible evidence, because guilt can only be established on such evidence.
8.1 Statements Made by the Taxpayer
An admission is important evidence but not conclusive. The person who made it can show that it is incorrect (Pullangode Rubber Produce Co. Ltd. v. State of Kerala, [1973] 91 ITR 18 (SC)). The courts have also made clear that the burden cuts both ways. In Bannalal Jat Constructions (P.) Ltd. v. ACIT (Rajasthan High Court, D.B. ITA No. 140/2018, decided on 31.08.2018), the Court refused to accept a retraction made at a belated stage without evidence of duress. A bare allegation of coercion raised much later carries little weight. The practical lesson for taxpayers is this: if a statement is recorded or a payment is made under pressure, the objection should be recorded promptly and in writing, not months later.
8.2 Statements of Co-accused
In fake-ITC investigations, the GST Department often relies on statements of entry operators or other suspects in the chain. The Honourable Supreme Court has consistently held that one co-accused’s confession is not substantive evidence against another. At best, it can lend assurance to a conclusion reached on other evidence (Haricharan Kurmi v. State of Bihar, AIR 1964 SC 1184). The Court applied the same principle to statements recorded by officers under a special statute in Surinder Kumar Khanna v. Intelligence Officer, DRI, (2018) 8 SCC 271, where a conviction resting only on co-accused statements was set aside. An arrest resting only on such statements, with no independent documentary or financial trail, is therefore open to challenge.
8.3 Loose Papers, Diaries and Seized Data
Entries in loose sheets are not “books of account”. Even entries in regular books are not enough by themselves to fix liability on a person without independent corroboration (CBI v. V.C. Shukla, (1998) 3 SCC 410). In Common Cause v. Union of India, (2017) 11 SCC 731, the Court held that loose papers and diary entries of this kind were not even enough to order an investigation against the persons named. Spreadsheets, chats and third-party records seized in GST searches should be assessed with the same caution.
8.4 Disclosure and Cross-examination after Arrest
Once proceedings move to adjudication or prosecution, material not disclosed to the taxpayer cannot be relied on (Kishinchand Chellaram v. CIT, (1980) 125 ITR 713 (SC)). Refusing cross-examination of witnesses whose statements form the basis of the case is a serious flaw that can make the order a nullity (Andaman Timber Industries v. CCE, 2015 (324) ELT 641 (SC)). In prosecution, Section 136 of the CGST Act adds a further condition. A statement recorded during an inquiry is relevant to prove its contents only if its maker is examined as a witness and the court admits the statement in the interests of justice or the maker cannot be produced (for example, because he or she has died or cannot be found).
8.5 In Summary
Together, these rulings give practical content to Radhika Agarwal. The question is not only whether the Commissioner had material, but whether that material was of a kind that could ultimately stand as evidence.
9. What Does the Supreme Court Ruling Mean for Businesses?
The decision creates a carefully balanced position.
9.1 For the GST Department
For the GST Department, it confirms that investigation and arrest powers are not dependent upon completion of adjudication. This can be especially relevant in cases involving suspected fake invoices, fraudulent ITC networks or deliberate tax evasion where authorities believe immediate action is required.
9.2 For Taxpayers
For taxpayers, however, the ruling provides an equally important protection: Section 69 arrest cannot rest on vague suspicion, standard language or unsupported assumptions.
There should be identifiable material, recorded reasons and an evidence-based basis for concluding that the conditions under Section 132 are satisfied.
9.3 Role of the Judiciary
Courts can still examine whether these statutory safeguards were followed, although judicial review does not mean that the High Court will conduct a full reassessment of the underlying GST dispute. The concurring opinion holding that the sufficiency or adequacy of the material behind the officer’s belief is not open to judicial review and that courts should intervene only for manifest arbitrariness or gross non-compliance with statutory safeguards. Arguments on the depth of judicial scrutiny are therefore likely to draw on both opinions.
10. The Key Takeaway
The question after the Honourable Supreme Court ruling is therefore no longer simply:
“Has tax liability been adjudicated before arrest?”
The more relevant question is:
“What credible material did the Commissioner have before forming the reason to believe that an arrest was justified?”
The Supreme Court has preserved the GST Department’s power to arrest before adjudication in appropriate cases, but it has simultaneously emphasised that personal liberty cannot be curtailed on the basis of suspicion alone.
For businesses facing GST investigation proceedings, the quality of the evidence, the quantification of the alleged offence and the reasons recorded by the authorities may therefore become just as important as the eventual tax demand itself.